
Skyline's $10M YouFit Bet: What It Signals for the HVLP Gym Market
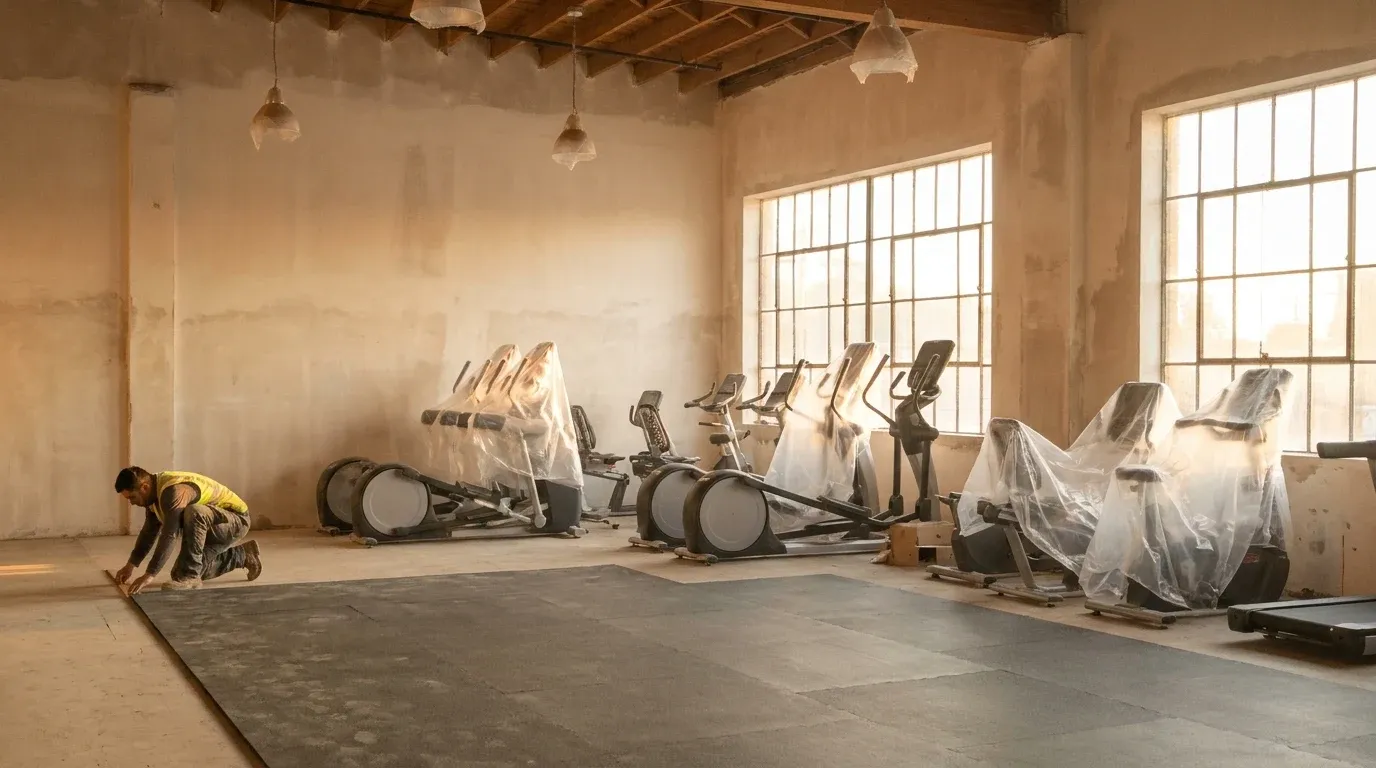
On November 13, 2026, Skyline Investors, a Los Angeles-based private equity firm with no prior fitness exposure, committed over $10 million to YouFit Gyms. The capital isn't funding new club openings. It's going straight into renovating existing locations. That distinction matters more than the dollar figure itself.
When a PE firm makes its first-ever move into an industry and immediately bets on yield improvement rather than footprint growth, it's worth asking what they're seeing that others aren't.
The Renovation Thesis, Explained
Skyline's capital allocation tells you something precise about how sophisticated outside money now reads the gym sector. The firm isn't buying into a rollup story. It isn't acquiring distressed assets at a discount and flipping them. It's directing resources at making existing YouFit clubs perform better per square foot. That's a fundamentally different operational bet.
In traditional gym investment cycles, growth equity meant site count. More doors, more members, more recurring revenue. The model worked when real estate was cheap, labor was manageable, and consumers were still forming gym habits post-2010. None of those conditions hold in 2026.
Renovation ROI is now competing seriously with new-unit ROI, and in many markets, it's winning. A refurbished club in an established trade area carries lower customer acquisition costs, retains existing members who might otherwise churn to a shinier competitor, and doesn't require the 12-to-18-month ramp that a cold open demands. For operators already sitting on underperforming square footage, the math is shifting fast.
What Planet Fitness's Q3 2026 Results Actually Said
The timing of Skyline's announcement is hard to separate from Planet Fitness's Q3 2026 earnings, released around November 15, 2026. The headline numbers were constructive: improved same-club sales and upgraded annual guidance. But the details told a more complicated story.
Planet Fitness flagged slower equipment placements and real estate delays alongside its membership growth numbers. It also acknowledged inconsistent promotional results, which is a significant admission from a brand whose entire commercial engine is built on high-volume, low-friction member acquisition. When the country's largest HVLP operator says its promotional cadence isn't landing consistently, the industry hears it.
The takeaway isn't that Planet Fitness is struggling. It isn't. But the Q3 print reinforced what operators have been quietly saying for two years: raw membership volume is no longer sufficient to drive investor confidence in this segment. Same-club productivity, ancillary revenue per member, and retention metrics are now the numbers that matter to capital allocators.
That framing aligns directly with what Skyline is doing at YouFit. If you're renovating existing clubs, you're betting that a better in-club experience drives those secondary metrics. Better equipment, improved layout, upgraded amenities. These aren't vanity upgrades. They're levers on member lifetime value.
The Twin Squeeze Facing Every HVLP Operator
The structural pressure on high-volume low-price operators isn't coming from one direction. It's two forces arriving simultaneously, and that combination is what makes Skyline's renovation play look increasingly rational.
First, wage inflation hasn't relented. Front desk labor, certified training staff, and facility maintenance workers all cost more than they did three years ago. For a gym charging $10 to $25 per month per member, there's limited room to pass those costs through without triggering the price sensitivity that defines the HVLP membership base.
Second, that price sensitivity is real and documented. The same consumers who chose an HVLP gym specifically because of the price point are not the members who absorb a $5 monthly fee increase without noticing. Any operator who's tested a price lift in the past 18 months has the churn data to prove it.
Caught between rising costs and sticky price ceilings, the logical lever becomes unit economics improvement. Spend capital on the existing estate, reduce churn through experience quality, and extract more value per member rather than chasing volume. That's the playbook Skyline is funding at YouFit, and it's the same logic that's driving broader conversations about capex-led differentiation across the HVLP tier.
This kind of strategic repositioning doesn't happen in isolation. It connects to the wider shift in gym business models that operators are navigating right now, including the downstream effects of GLP-1 adoption on membership composition and service demand. If you want context on how pharmaceutical trends are intersecting with gym revenue models, how GLP-1 drugs are reshaping gym business models is worth your time.
What "Capex-Led Differentiation" Actually Means in Practice
The phrase sounds abstract. The execution isn't. For HVLP operators, capex-led differentiation means making deliberate, measurable investments in the physical club environment that justify either a modest price premium, a retention advantage, or both.
This can take several forms. Equipment refresh cycles that keep the floor current with what members see at higher-priced competitors. Recovery zones with stretching areas, foam rolling stations, or basic mobility equipment that extend post-workout dwell time. Lighting and locker room upgrades that signal quality without requiring a boutique price point. Personal training infrastructure that supports a more professional coaching environment.
That last point matters operationally. A better-equipped club creates the conditions for a stronger personal training revenue line, but only if the coaching product itself holds up. Members who invest in one-on-one sessions are higher-value and lower-churn. Getting that right starts before the first session. If you're building or refining your gym's personal training program, understanding how to present coaching credentials and professionalism to prospective members is part of the equation. How to vet a trainer: certs, insurance, red flags gives you the member-facing perspective on what quality signals look like.
The analytical infrastructure behind these decisions is also evolving. The ability to track renovation ROI at the club level, attribute retention improvements to specific capital investments, and model payback periods on equipment spend is becoming a core competency for serious operators. FitnessKPI's $1.4M raise signals a BI gap in gym ops examines why that capability is now a competitive differentiator rather than a back-office function.
The Strategic Question for Independent and Regional Operators
If you're running an independent gym or a regional chain with five to thirty locations, the Skyline-YouFit deal frames a decision you may already be postponing. Is renovation ROI now more defensible than new-unit growth in a capital-constrained environment?
The honest answer is: it depends on your existing estate quality, but for most operators who opened clubs between 2015 and 2020, that estate is now showing its age. Equipment that was new six years ago is mid-cycle. Layouts designed before functional training became a mainstream expectation may feel dated. Recovery and mobility spaces that didn't exist in the original build are now something members compare you against.
Opening a new club requires site selection, lease negotiation, buildout, staffing, and a ramp period where you're burning cash without full membership revenue. Renovating an existing club with an established member base, known trade area dynamics, and trained staff is a fundamentally different risk profile. That doesn't mean it's always the right call. But the bar for justifying new-unit growth has risen considerably, and Skyline's bet suggests institutional capital is reaching the same conclusion.
The broader trend here also connects to how premium wellness services are expanding into the fitness space. As club environments improve, the boundary between gym and wellness destination continues to blur. Drip Gym goes national: what at-home IV therapy signals for brands captures one dimension of that convergence, showing how ancillary wellness revenue streams are reshaping what a gym membership can mean to a consumer.
What 2027 Looks Like If This Playbook Spreads
If Skyline's renovation thesis proves out at YouFit over the next 18 to 24 months, the signals will be visible in the data: lower churn at renovated clubs, higher personal training attach rates, improved same-club revenue. If those numbers materialize, expect more capital to follow the same logic.
That would accelerate a bifurcation already underway in the HVLP tier. Operators who invest in their existing estate will increasingly look like a different category from those who don't. Members comparison-shopping between two $20-per-month gyms in the same zip code will make decisions based on equipment quality and facility feel. The price point may be identical. The experience won't be.
For operators still weighing where to direct limited capital, the message from Skyline's first fitness investment is unusually clear. The era of assuming that more locations automatically means more value is over. The operators heading into 2027 with the strongest positions will be the ones who decided to get more out of what they already have.